Fraud risk assessment starts before an auditor selects invoices or checks bank balances. For Canadian businesses, audit accounting firms examine how money moves, who can override controls and where financial statements could be deliberately misstated. The aim is to identify risks of material misstatement due to fraud and design audit procedures that respond to them.
That distinction matters. A financial statement audit provides reasonable assurance, not a guarantee that every theft, false expense or concealed transaction will be discovered. Management remains responsible for preventing and detecting fraud, with oversight from those charged with governance.
For business owners in Oakville and the Greater Toronto Area, understanding this process makes audit preparation more useful. It helps explain why auditors ask questions about incentives, request evidence outside the accounting system and challenge transactions that initially appear routine.
What audit accounting firms are responsible for
In Canada, Canadian Auditing Standard 240 addresses the auditor’s responsibilities relating to fraud in a financial statement audit. The Auditing and Assurance Standards Board establishes Canadian auditing standards.
Auditors focus on two broad sources of fraud-related misstatement:
- Fraudulent financial reporting: Deliberately changing reported results, omitting liabilities or manipulating estimates to mislead financial statement users.
- Misappropriation of assets: Stealing cash, inventory or other assets, sometimes accompanied by altered records that conceal the loss.
An error can produce the same incorrect balance as fraud. The difference is intent, which may be difficult to establish from accounting records alone. Auditors assess evidence and its financial reporting implications rather than make legal determinations about whether someone committed a crime.
Fraud is also harder to detect when it involves collusion, forged documents or senior management overriding established controls. Professional skepticism means questioning contradictory evidence and not treating a trusted employee’s explanation as sufficient support.
A bookkeeping, compilation or review engagement is not equivalent to an audit. Owners should confirm the engagement type and its assurance level before assuming that fraud-focused audit procedures are included.
How the fraud-risk assessment works
Understand the business and its pressures
Before choosing detailed tests, audit accounting firms build an understanding of the business model, ownership structure, financing arrangements and reporting requirements. A construction contractor with progress billings presents different risks from a retailer holding valuable inventory.
The assessment considers incentives and pressures, opportunities to commit fraud and attitudes that could justify dishonest behaviour. These are risk factors, not proof that fraud has occurred.
A company approaching a lending covenant limit, for example, may face pressure to overstate earnings. A commission plan based entirely on booked sales could create incentives to record transactions before the recognition criteria are met.
Auditors make inquiries of management, those charged with governance and other relevant personnel. Where applicable, this includes internal audit. They may ask about known allegations, unusual transactions, whistleblower reports and how management monitors fraud risks.
Financial analysis adds context. Unexpected margin improvements or persistent gaps between profit and cash flow deserve explanation. A structured approach to investigating budget variances can help distinguish commercial changes from unsupported adjustments, although an unusual variance alone does not establish fraud.
Follow transactions and evaluate controls
A written policy is not evidence that a control operates. Auditors may trace a transaction from initiation through authorization, processing and recording to understand what actually happens.
For example, a supplier payment walkthrough might reveal that the same employee can create a vendor, change its banking details and release payment. That concentration of access creates an opportunity for diversion, even if no suspicious payment has yet been found.
During this work, audit accounting firms evaluate the design of relevant controls and determine whether they have been implemented. If the audit strategy relies on controls, their operating effectiveness must also be tested.
In a smaller business, full segregation of duties may be impractical. A genuine owner review can help, but it needs substance: access to original bank records, scrutiny of new suppliers and evidence that exceptions were followed up.
An approval signature carries little weight if the approver never sees the supporting information or can be bypassed without detection.
Connect each risk to a possible misstatement
A useful assessment goes beyond saying that “payroll is risky.” It identifies what could go wrong, which account or disclosure would be affected and what evidence could address the concern.
| Business area | Possible fraud scenario | Potential audit response |
|---|---|---|
| Revenue | Sales recorded before goods are delivered | Examine contracts, dispatch evidence and transactions around year-end |
| Purchasing | Payments made to a fictitious supplier | Inspect vendor changes, supporting documents and payment destinations |
| Payroll | Payments continue for a departed employee | Compare payroll records with personnel records and departure dates |
| Inventory | Missing stock remains in the accounting records | Observe counts, perform test counts and investigate discrepancies |
| Estimates | An allowance is reduced to inflate profit | Challenge assumptions and compare prior estimates with actual outcomes |
These are illustrations, not a universal checklist. Audit accounting firms tailor their assessment to the entity and the applicable financial reporting framework. A procedure that addresses whether a transaction occurred may not establish that its amount is correct.
Auditors ordinarily presume that fraud risks exist in revenue recognition. They assess which revenue streams, transactions or assertions create those risks and document their reasons if they conclude that the presumption is not applicable.
How the assessment changes the audit work
Identifying a fraud risk should change the nature, timing or extent of audit procedures. Simply requesting more documents of the same type may not address the underlying concern.
For suspected premature revenue recognition, auditors might inspect delivery evidence and customer acceptance terms rather than rely only on invoices. For questionable cash balances, obtaining evidence directly from the financial institution can be more persuasive than reviewing a statement supplied by management.
Other responses may include examining transactions closer to year-end, selecting unexpected locations for testing or involving specialists where necessary. The appropriate response depends on the assessed risk and circumstances.
The reliability of the underlying data matters too. Before analysing an exported sales ledger, auditors need to consider whether it is complete and accurate. A sophisticated analysis of an incomplete file can miss the very transactions that matter.
Independent evidence helps audit accounting firms challenge explanations rather than merely collect them. However, an external document is not automatically conclusive: its source, authenticity and relevance still require consideration.
Why management override receives specific attention
Even a well-designed control environment can be undermined by someone with sufficient authority. Management override therefore requires attention across audits, not only in businesses with obviously weak processes.
Audit procedures addressing this risk include testing journal entries and other adjustments, reviewing estimates for possible bias and evaluating the business rationale for significant unusual transactions.
A journal entry posted late at night is not inherently fraudulent. It becomes more concerning when combined with an unusual account combination, missing support or an explanation that conflicts with other evidence. Similarly, a large year-end transaction deserves scrutiny when its commercial purpose is unclear.
When evaluating estimates, audit accounting firms consider whether individually plausible judgements collectively point in one direction. Repeatedly choosing assumptions that improve earnings can indicate bias even when no single assumption looks extreme.
Past estimates also provide useful evidence. Comparing them with subsequent outcomes can reveal patterns that warrant further investigation, while allowing for genuine changes in circumstances.
Example: fraud risks in high-value retail inventory
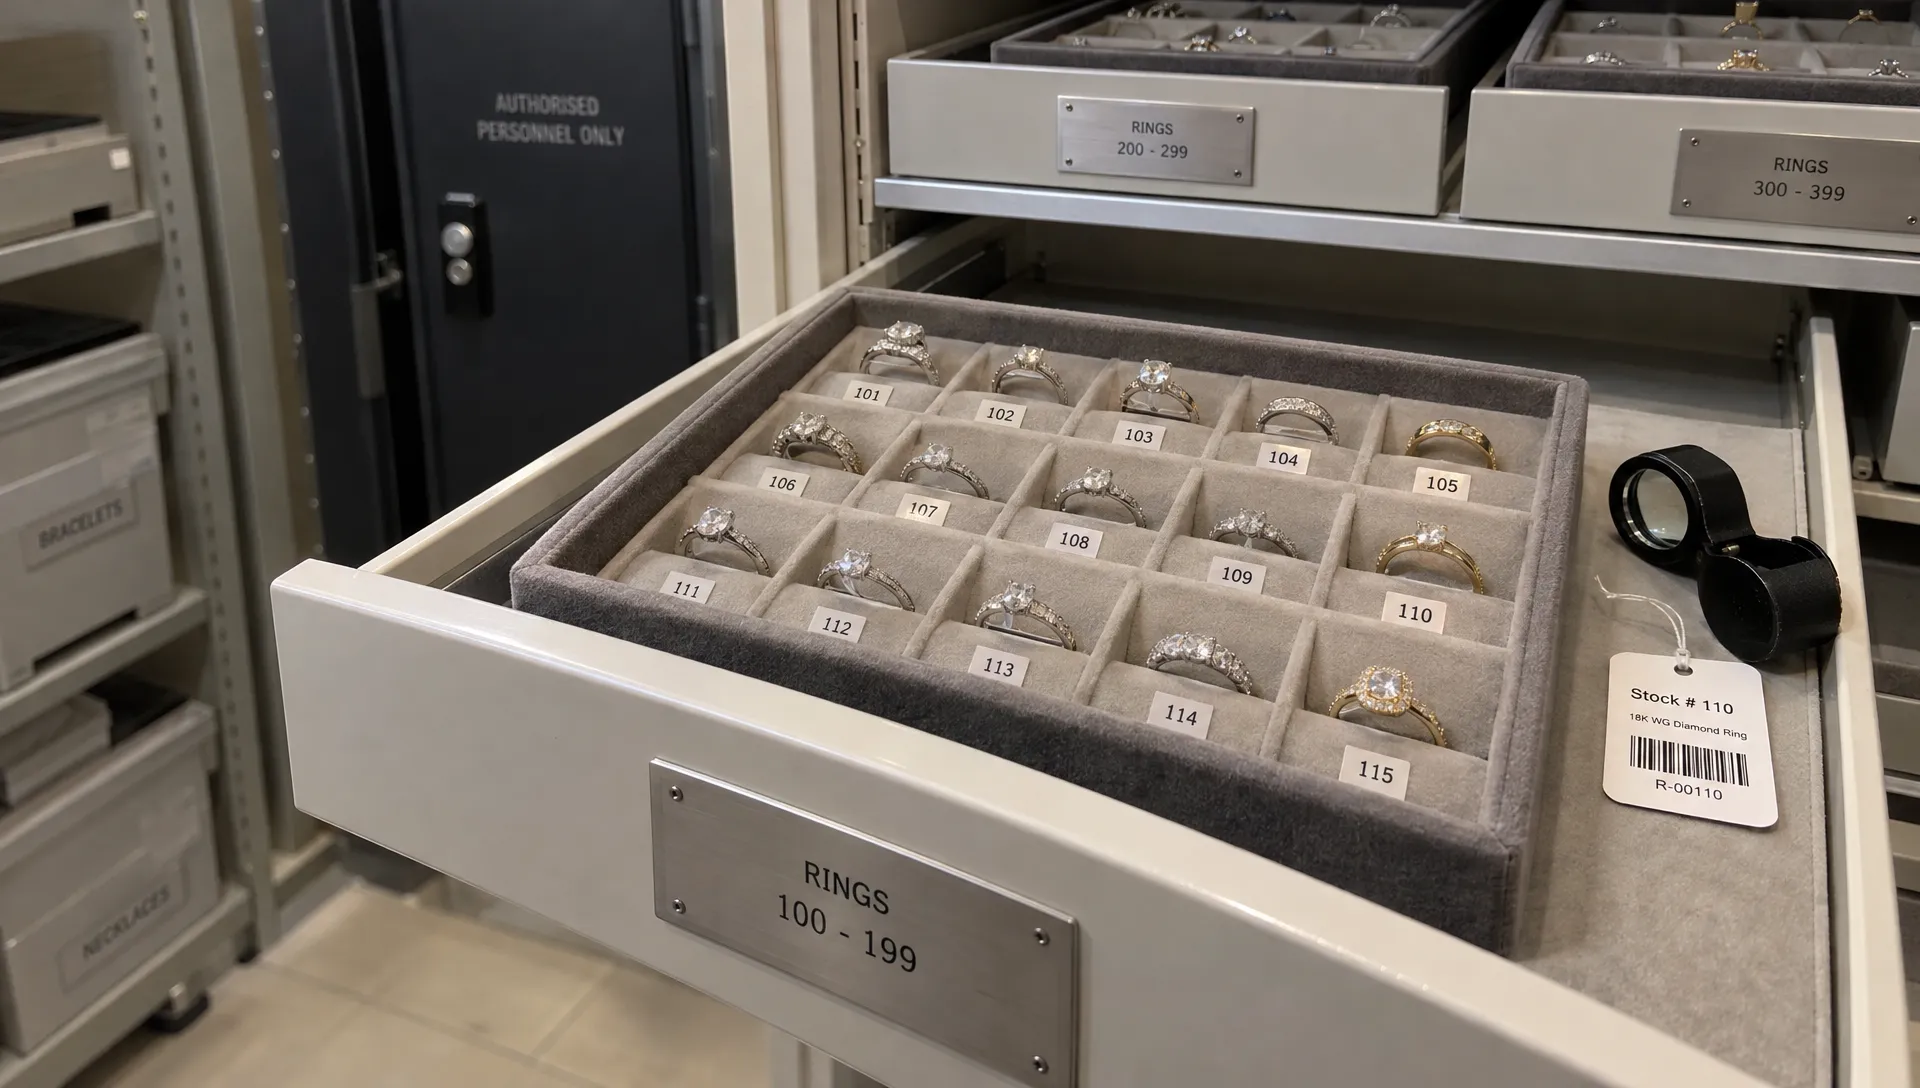
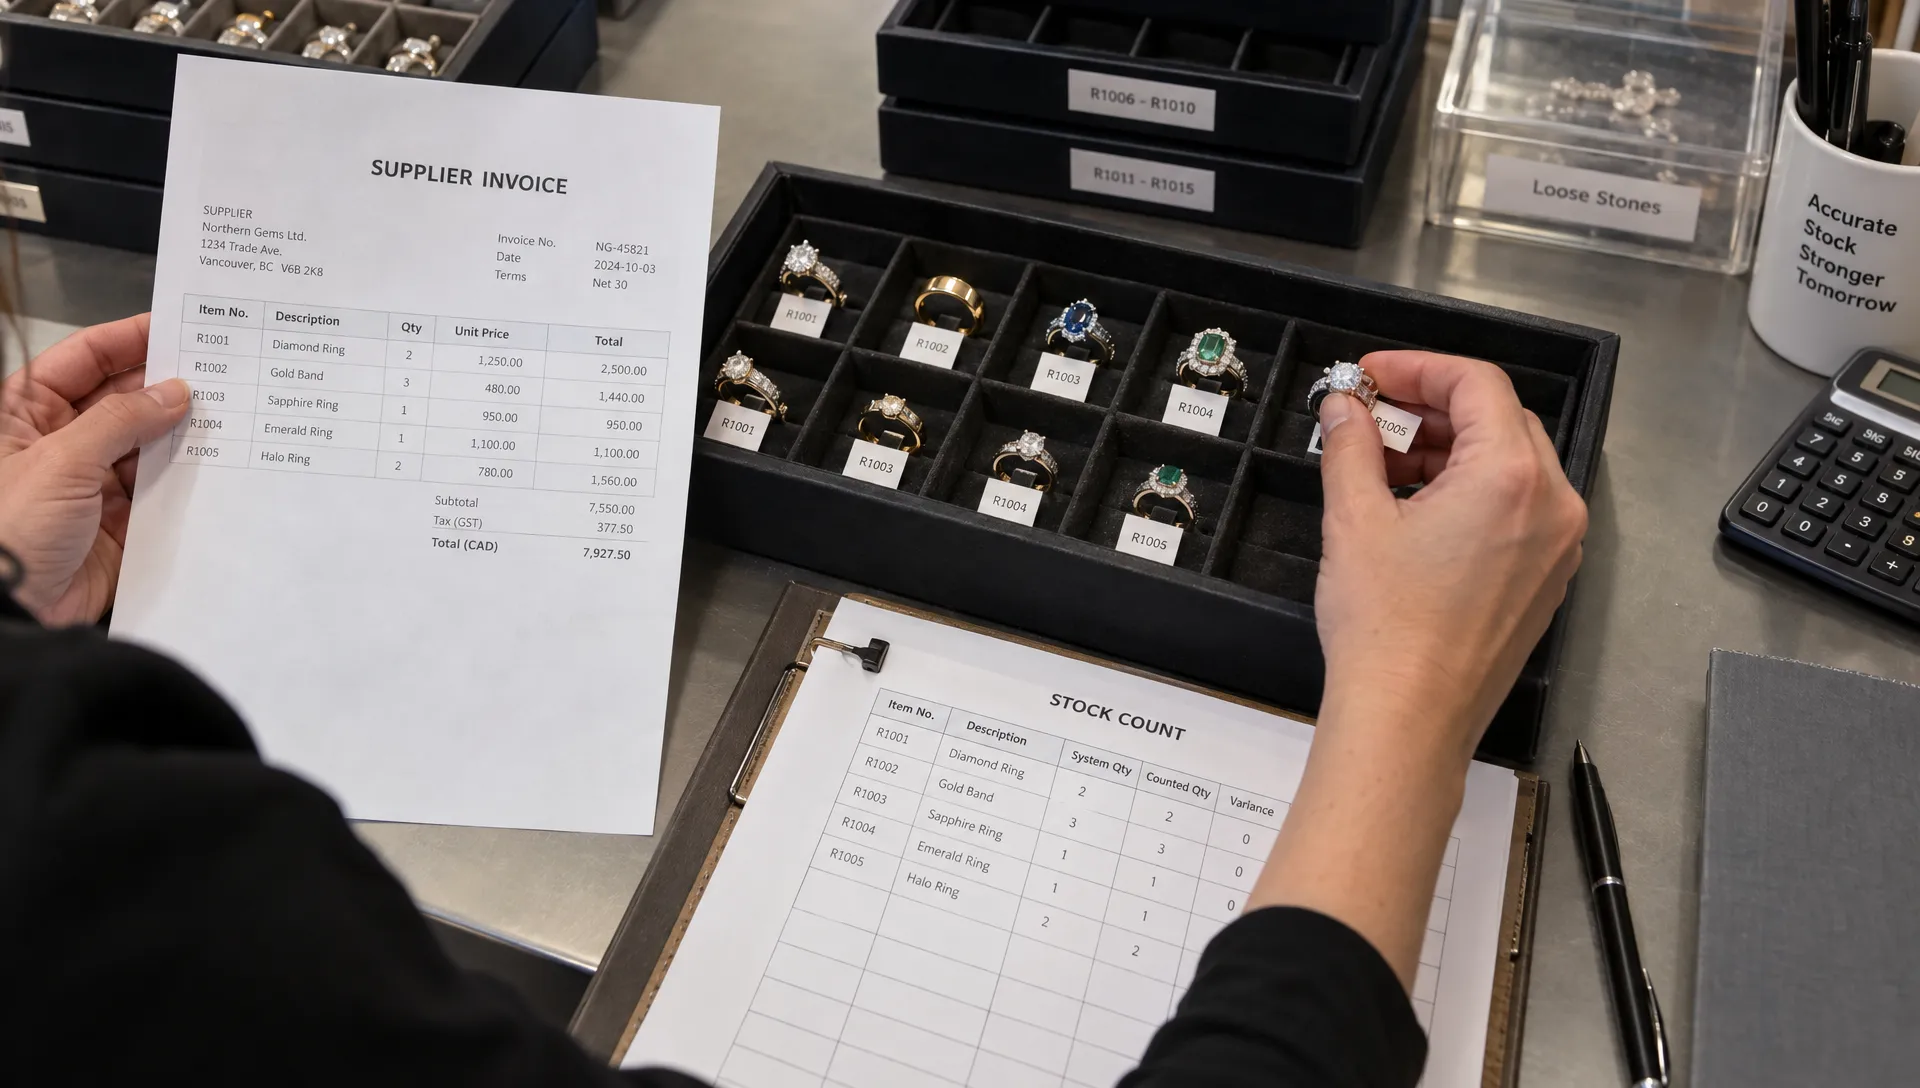
Consider a jewellery retailer with compact, valuable products and frequent custom orders. Its risks may include missing stock, substituted stones, unrecorded customer deposits or inventory recorded at an unsupported value.
Consumer-facing engagement ring buying factors such as stone type, certification and customization illustrate why an inventory description of “one ring” may be insufficient. Records need to distinguish the item actually held and connect it to relevant purchase and product documentation.
An auditor might compare selected physical items with stock records, examine supplier invoices and investigate differences between inventory movements and sales. Customer deposits also need to be reconciled with orders and the applicable revenue recognition treatment.
For this business, audit accounting firms would distinguish evidence of existence from evidence of valuation. Seeing a ring establishes something different from verifying its recorded cost, ownership or potential write-down. A product certificate alone does not establish all those points.
The broader lesson applies to equipment dealers, electronics distributors and other businesses holding high-value stock: controls and audit evidence need to reflect the specific assets, not just the total inventory balance.
What happens when an auditor finds a red flag?
A discrepancy triggers further work, not an immediate accusation. Auditors seek explanations, obtain corroborating evidence and assess whether the issue is isolated or suggests a wider problem.
Suppose a customer disputes a receivable that management says is valid. The auditor may examine the contract, correspondence, delivery records and subsequent receipts. Depending on the findings, similar transactions may require additional testing.
An identified or suspected fraud can also affect the assessment of management integrity and the reliability of other representations. Audit accounting firms may need to revise their risk assessment and reconsider evidence already obtained.
Communication depends on who may be involved and the significance of the matter. Concerns involving management generally require communication at an appropriate governance level rather than solely with the person implicated.
Possible outcomes include proposed financial statement adjustments, communication of control deficiencies, additional procedures or implications for the audit opinion. Legal and regulatory reporting responsibilities depend on the circumstances; an auditor may need legal advice rather than assume every concern follows the same reporting route.
How owners can prepare without prejudging employees
Good preparation makes transactions easier to explain and exceptions easier to resolve. It does not require treating every employee as a suspect.
Before fieldwork, management should assemble current process descriptions, approval authorities, system-access information and supporting schedules for significant balances. Reconciliations should identify unresolved differences rather than hide them in unexplained adjustments.
Changes during the year deserve particular attention. New payment platforms, staff departures, acquisitions or expanded remote access can alter risks even when the business’s revenue has stayed stable.
Businesses can help audit accounting firms by making relevant personnel available and providing original supporting records where requested. Management should also disclose known or suspected fraud and relevant allegations, rather than deciding unilaterally that an issue is too small to mention.
Where a full separation of duties is not feasible, document the compensating review: who performed it, what they examined and how they resolved exceptions. This is more useful than a policy that describes controls the business cannot realistically operate.
Frequently asked questions
Does a financial statement audit guarantee that fraud will be found? No. An audit provides reasonable assurance that financial statements are free from material misstatement, whether caused by fraud or error. Concealment, collusion and management override create detection challenges, and immaterial fraud may fall outside the audit’s scope.
Is a fraud-risk assessment the same as a forensic investigation? No. A financial statement audit assesses fraud risks to support the audit opinion. A forensic investigation usually addresses a specific allegation or concern under a separately defined scope and may support legal proceedings.
Will auditors test every transaction? Usually not. Audit accounting firms use risk-based procedures, which may include sampling, targeted selections or testing an entire population where appropriate. The objective is sufficient appropriate evidence, not automatic inspection of every entry.
Should an owner wait for the audit to report suspected fraud? No. Raise concerns promptly through an appropriate channel. If management may be involved, consider the governance structure and obtain independent professional or legal advice about preserving evidence and next steps.
Turn the assessment into stronger financial oversight
Fraud-risk assessment is most useful when it leads to clearer responsibilities, supportable records and attention to control gaps. It should also be clear which work belongs to an audit and which requires separate advisory or investigative support.
For Oakville and GTA businesses, Reach Professional Accounting offers accounting, audit and assurance, and business advisory services. Discuss your reporting requirements and control concerns through its business advisory team to determine an appropriate scope of support.