Choosing the best accounting firm for your tech startup means finding a team that can support your next business decision, not just file your next tax return. A pre-revenue software company, a growing SaaS business and a hardware startup preparing for investment need different kinds of help.
For founders in Oakville and the Greater Toronto Area, the challenge is separating relevant expertise from a polished proposal. Start with the work you need, then compare firms on evidence, accountability and total cost.
Define the job before you build a shortlist
Write down your next significant financial milestone. It might be hiring your first employees, extending your cash runway, closing a funding round or expanding outside Canada. That milestone should shape the engagement.
| Startup situation | Immediate accounting priorities | What to ask a prospective firm |
|---|---|---|
| Pre-revenue or founder-funded | Reliable books, expense records and filing obligations | Who keeps the records current and flags upcoming deadlines? |
| Early customer revenue | Monthly reporting, receivables and revenue recognition | How will you turn billing activity into dependable financial statements? |
| Preparing for investment | Forecasts, historical reconciliations and due diligence support | What must be cleaned up before investors review the numbers? |
| Growing team or international sales | Payroll, tax coordination and financial oversight | Which work can you handle directly and where are specialists needed? |
Separate essential work from optional advice. You may need monthly bookkeeping and quarterly financial guidance rather than a large ongoing advisory package. Conversely, low-cost year-end preparation will not solve a weekly cash shortage.
How to evaluate the best accounting firm for a tech startup
Ask candidates to describe businesses they support that resemble yours in revenue model, stage and complexity. Confidentiality may prevent them from naming clients, but they should still be able to explain the problems they have handled and their approach.
“Technology experience” needs unpacking. Advising an ecommerce merchant is not the same as supporting a software developer. For example, an online retailer selling natural diamond engagement rings needs inventory and cost-of-sales expertise. A SaaS startup needs a clear approach to subscription contracts, deferred revenue and development spending. Both require sound accounting, but the technical questions differ.
Ask which accounting framework applies to your company and whether an investor’s reporting requirements would change the work. Do not assume fundraising automatically requires an audit. Confirm what the investor, lender or agreement actually requires before purchasing an assurance engagement.
A compilation does not provide assurance. Reviews and audits provide different levels of assurance, so proposals for those services are not interchangeable.
The best accounting firm should explain these distinctions in plain language and connect its recommendations to a specific requirement, rather than selling the most extensive package by default.
Look for reporting that supports operating decisions
A startup’s financial statements should reconcile to its underlying records. Attractive dashboards cannot compensate for missing transactions, unreconciled payment accounts or inconsistent expense treatment.
Ask to see an anonymized reporting package or a clearly labelled sample. Look for a balance sheet, income statement and cash-flow information, supported by explanations of material changes. Confirm when you will receive the reports and what you must provide to meet that timetable.
For a subscription business, ask how the firm distinguishes cash collected from revenue earned. Reach Professional’s guide to accounting for businesses with subscription revenue explores that issue in more detail.
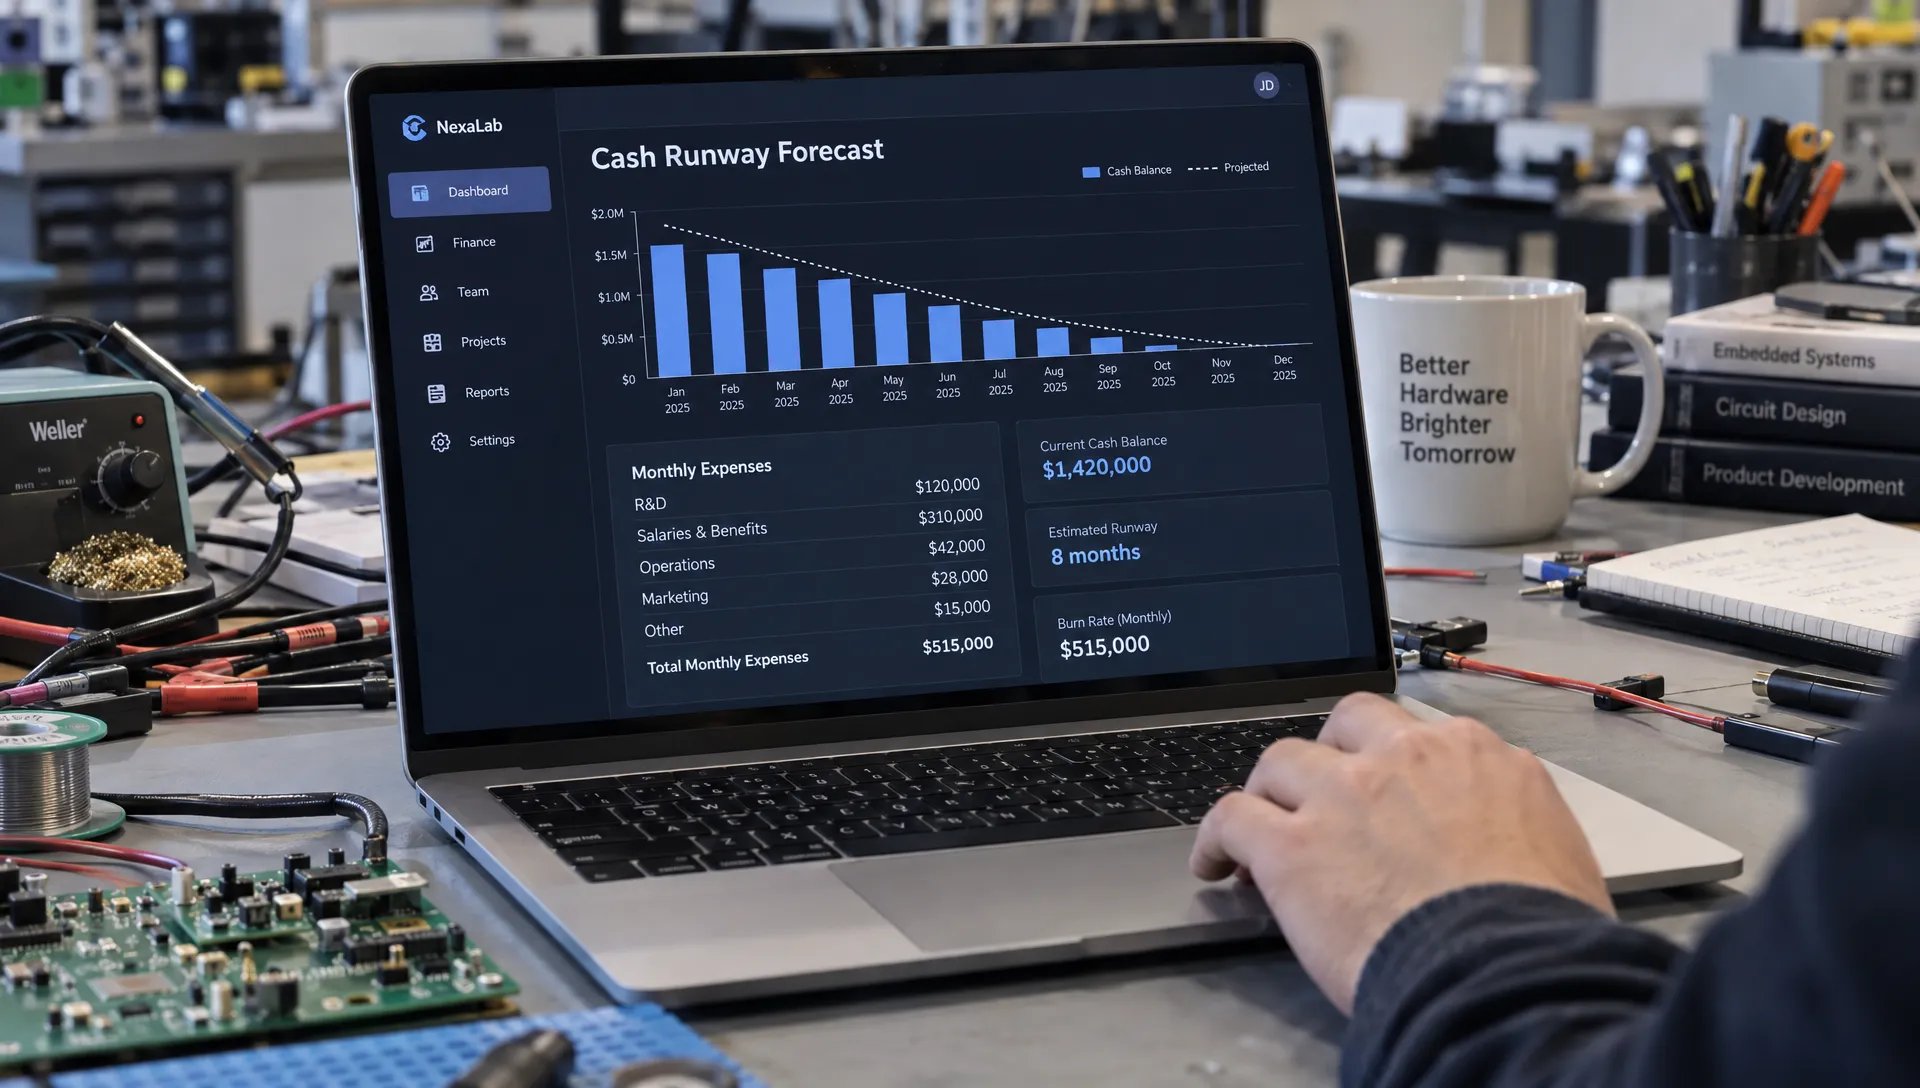
Then test whether the accountant can translate reporting into a decision. Give a hypothetical example: your company is considering another developer while customer payments are arriving later than expected. Ask what information the firm would request before recommending a hiring date.
A useful response should address available cash, expected collections, payroll commitments and the uncertainty in the forecast. It should not simply divide the bank balance by last month’s expenses.
When comparing candidates, the best accounting firm is the one that can explain both the numbers and the assumptions behind its advice, including what could make the forecast wrong.
Check Canadian tax depth without buying a refund promise
Your firm should identify which Canadian obligations apply to your business, including corporate income tax, GST/HST and payroll remittances. Ask who prepares filings, who reviews them and who tracks deadlines. Also establish who responds if the Canada Revenue Agency requests supporting information.
For eligible research and development, discuss the CRA’s Scientific Research and Experimental Development tax incentives. Routine development does not qualify merely because it involves code. Eligibility depends on the work performed and the applicable requirements.
Ask how a candidate evaluates potential claims, what technical and financial records it expects and whether a separate specialist participates. Be cautious about refund promises made before anyone has reviewed your activities, expenditures or corporate circumstances.
International sales add another layer. Customer location, contract terms and the nature of the supply can affect tax treatment. A Canadian firm should explain the limits of its advice and when foreign tax expertise is necessary, rather than treating every overseas sale the same way.
The best accounting firm will also distinguish tax planning from claim preparation. You need advice early enough to keep appropriate records and make informed decisions, not a last-minute request to reconstruct a year of development work.
Test the people and process, not just the proposal
The partner presenting the proposal may not be your regular contact. Before signing, establish who prepares your work, who reviews it and who takes responsibility when something is unclear.
Use the consultation to ask practical questions:
- Who will answer routine questions, and what response time should we expect?
- What information must we submit each month, and by when?
- How will you tell us about missing records or an approaching deadline?
- What happens when our usual contact is unavailable?
- Which decisions or transactions should we discuss with you in advance?
Verify the relevant professionals’ credentials through the appropriate provincial body, such as CPA Ontario. Where assurance services are involved, confirm that the firm has the authorization needed for the engagement.
Security deserves the same attention as responsiveness. Ask how documents are exchanged, how account access is controlled and whether individual permissions can be revoked. Avoid arrangements that depend on sharing a founder’s banking password. Clarify how your records will be retained and returned when the relationship ends.
References can help validate the proposed working relationship. With permission, speak to a client with similar complexity and ask about reporting consistency, unexpected charges and how mistakes were resolved.
The best accounting firm should make responsibility visible before work begins. A friendly meeting is encouraging, but a defined process is stronger evidence of dependable service.
Compare candidates with a weighted scorecard
A scorecard makes it harder for a recognizable name or an unusually low quote to dominate the decision. Choose the criteria before reviewing final proposals, then score every candidate against the same evidence.
The following weights are illustrative, not an industry standard. Adjust them to reflect your next milestone.
| Criterion | Suggested weight | Evidence to request |
|---|---|---|
| Relevant business-model experience | 25% | Comparable situations and explanations of technical issues |
| Reporting and decision support | 25% | Sample reports, close timetable and forecasting approach |
| Canadian tax capability | 20% | Clear responsibilities, review process and specialist boundaries |
| Service delivery and security | 15% | Named contacts, access controls and communication expectations |
| Scope and fee transparency | 15% | Written inclusions, exclusions and additional-work terms |
Score each category from one to five, then apply the weights. Keep a short note explaining each score so you can distinguish demonstrated capability from a good sales presentation.
Use minimum requirements as well. A candidate should not remain on the shortlist if it cannot explain who is responsible for filings or how you will retrieve your records, regardless of its overall score.
If two firms finish close together, ask both to address the same unresolved scenario. Their follow-up may reveal more than another general introductory meeting.
Compare total cost and protect your ability to switch
A monthly price means little without a defined scope. Confirm whether it includes bookkeeping, year-end statements, corporate tax preparation, sales tax filings, payroll support and scheduled advice. Ask how transaction volume, additional entities or cross-border activity affect fees.
Initial cleanup deserves separate attention. A low recurring quote can look less attractive if historical reconciliations, opening balances and software migration are substantial additional projects. Request an estimate for onboarding and a process for approving work beyond that estimate.
Likewise, clarify what “advisory included” means. A scheduled forecast review is different from access to occasional answers by email. Neither arrangement is inherently better, but you should know what you are buying.
Review the engagement letter before accepting. Reach Professional’s explanation of what trusted tax services put in an engagement letter can help you assess scope, responsibilities and filing arrangements.
Confirm ownership and access for accounting subscriptions, source documents and exported records. Ask about notice periods, outstanding fees and the handover process if you change providers.
For your budget, the best accounting firm is not necessarily the cheapest. It is the firm whose fees correspond to clearly defined work, with manageable onboarding costs and no ambiguity about what remains your responsibility.
Agree on the first 90 days
Before committing, ask the preferred firm for a realistic onboarding sequence. This should reflect the state of your records rather than promise instant clarity from incomplete information.
The initial phase should establish access, identify missing documents and confirm upcoming obligations. Next comes reconciliation and correction of material issues, followed by an agreed reporting timetable. If urgent filings or payroll deadlines intervene, the firm should explain how priorities will change.
Choose a few observable outcomes. Examples include reconciled bank and payment accounts, a documented filing calendar, a first monthly reporting package and a cash forecast with stated assumptions. These are proposed engagement goals, not services every firm automatically includes.
Schedule a review after the first reporting cycles. Discuss whether reports arrive as agreed, explanations are useful and the scope still fits. Resolve gaps before adding more services.
Even the best accounting firm needs timely information from your team. Assign an internal owner for document requests and decisions so the engagement does not stall between the founder, bookkeeper and accountant.
Frequently asked questions
Should a startup choose a Big Four firm or a smaller practice? Deloitte, EY, KPMG and PwC make up the Big Four. A startup may benefit from a large firm’s specialist resources when its needs are complex, but size alone does not establish fit. Compare the actual team, relevant expertise, service scope and fees.
Does a tech startup need a fractional CFO immediately? Not necessarily. First establish reliable bookkeeping and reporting. Fractional CFO support becomes more useful when you need recurring help with forecasts, funding decisions, hiring plans or financial oversight. Define those decisions before committing to an ongoing arrangement.
Can an accountant guarantee a successful SR&ED claim? Treat guarantees cautiously. A sound assessment requires reviewing the work and expenditures against the program’s requirements. Ask how eligibility is evaluated, what evidence is needed and what support is included if the CRA reviews the claim.
Does the firm need to be near our office? Physical proximity can make meetings easier, but secure systems and reliable communication also support remote working relationships. The best accounting firm for an Oakville startup should understand the applicable Canadian requirements and deliver consistently, whether meetings happen locally or online.
Start with a clearly defined conversation
Before requesting proposals, prepare a one-page summary of your business model, current records, team size and next financial milestone. Include the questions you need answered and any known reporting or filing requirements.
For Oakville and GTA founders considering additional financial guidance, explore Reach Professional’s business advisory services and discuss your priorities. Use the conversation to establish fit, responsibilities and scope before deciding which support your startup needs.