An engagement letter tells you what your accountant will do, what you must provide and where the assignment ends. When choosing trusted tax services, this document deserves as much attention as the fee quote. A clear letter helps prevent missed deadlines, unexpected charges and assumptions about who is handling a particular return.
For business owners in Oakville and across the GTA, the practical question is straightforward: does the agreement describe the work you actually need? Before signing, check that it addresses the following points in language you understand.
Identify the client and the period covered
The letter should name the accounting firm and the person or legal entity receiving the service. That distinction matters when an owner has a corporation, a separate sole proprietorship and personal tax obligations. An engagement to prepare the corporation’s return does not automatically include the shareholder’s personal return.
Look for the relevant tax year, fiscal year-end or reporting periods. “Annual tax services” is less useful than a description identifying the specific returns and periods involved. If the arrangement continues from year to year, the letter should explain how its terms are renewed or updated.
It should also identify the appropriate client contact and who can approve additional work. For a corporation with several owners, this reduces uncertainty about whose instructions the firm may accept. When different entities have different needs, separate letters or clearly separated schedules can make the responsibilities easier to follow.
What trusted tax services include in the scope
The scope should name the deliverables, not simply promise “tax support”. Depending on your circumstances, the agreement could cover some of the following services. None should be assumed to be included unless stated.
| Service | What the letter should clarify |
|---|---|
| Personal tax preparation | Whose T1 return is included and for which year |
| Corporate tax preparation | Which corporation’s T2 return is included and whether related schedules are covered |
| GST/HST compliance | Which reporting periods and returns the firm will prepare or file |
| Payroll-related filings | Whether T4 slips, summaries or other information returns are included |
| Tax planning | Whether advice is included, separately quoted or outside the engagement |
| CRA correspondence | Whether notices, enquiries and reviews are covered after filing |
Preparation, review and submission are different activities. The agreement should state which ones the firm will perform. It should also explain whether bookkeeping corrections or financial statement preparation are prerequisites, included tasks or separately billed work.
If you need accounting and financial statement services alongside tax preparation, confirm how those assignments fit together. Preparing a tax return does not, by itself, provide an audit or assurance on the underlying records.
Allocate responsibilities and distinguish the deadlines
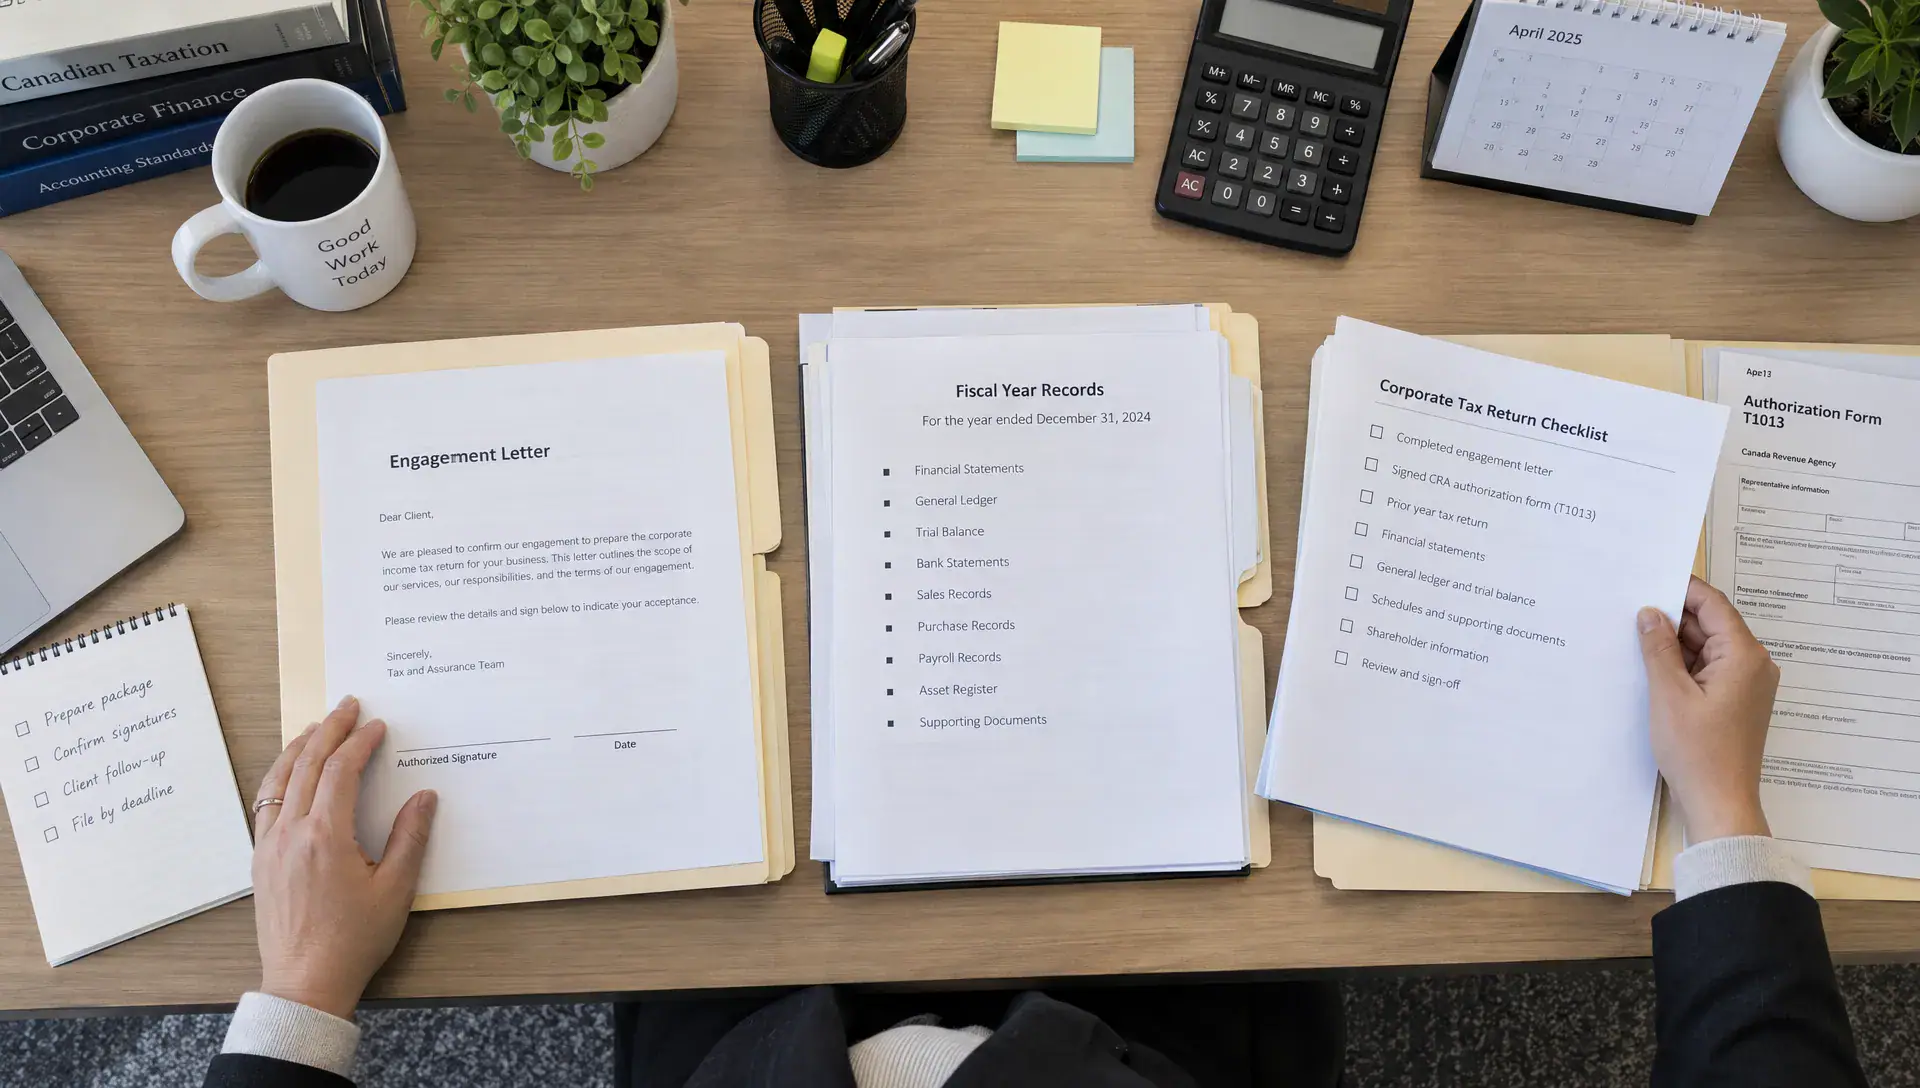
With trusted tax services, the engagement letter should make the division of work visible. The firm needs to describe its responsibilities, while the client’s obligations should include supplying complete records, answering questions and reviewing information before approving a return.
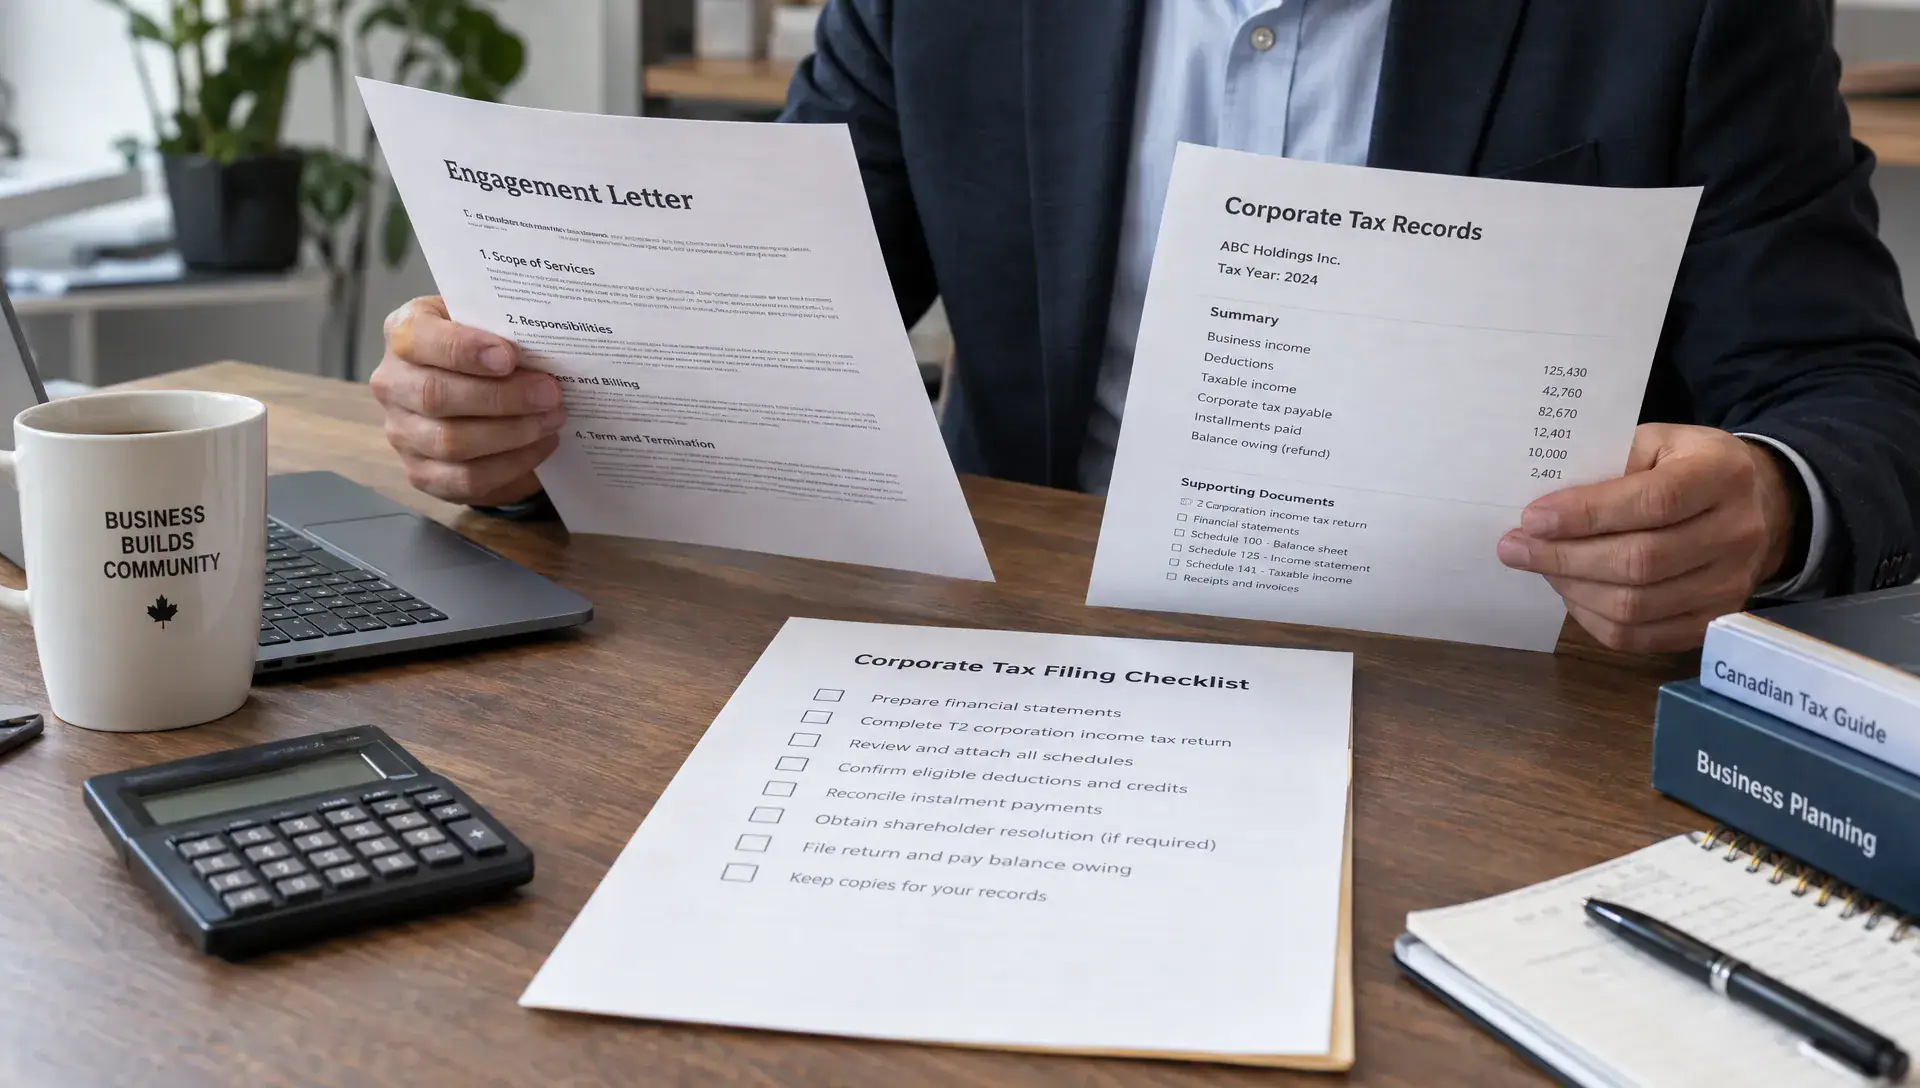
For businesses, the required records might include bookkeeping files, bank statements, payroll reports, prior-year returns and details of significant transactions. The letter should establish when those records are due and how missing information will be handled. A document checklist can sit alongside the agreement without making the letter unnecessarily long.
A filing deadline and a payment deadline are not necessarily the same. Ask who will calculate amounts owing, communicate payment instructions and make the actual payment. The firm’s internal document deadline should also be distinguished from the statutory deadline. Sending records on the last filing day may not leave enough time to complete the work.
Disclose income outside your usual operations, too. A contractor or property manager participating in an arrangement such as TapTech’s water treatment partnership program should share details of any referral payments and the related agreement. Confirm whether assessing those payments, their GST/HST implications and supporting records falls within the tax assignment.
Separate CRA authorization from approval to file
Even when you use trusted tax services, signing an engagement letter does not automatically authorize the firm to access your Canada Revenue Agency account. Representative authorization is a separate process, with access that depends on the authorization granted.
The CRA’s Represent a Client service explains how representatives can access tax information and services for clients. Your agreement should clarify whether the firm needs this access, what it will use it for and who is responsible for completing the authorization steps.
Approval to electronically file a return is another separate requirement. Where applicable, the firm should obtain the relevant signed filing authorization, such as Form T183 for an individual return or T183CORP for a corporate return. The engagement letter should describe the review and approval process rather than treating your initial signature as blanket approval of a return you have not yet seen.
Also clarify how confirmation will be provided after submission. A completed draft, a signed authorization and an accepted electronic filing represent different stages. Knowing which confirmation to expect helps you distinguish work in progress from a return that has actually been filed.
Explain fees and how additional work is approved
The fee section should identify whether the work is billed at a fixed price, hourly or under another agreed arrangement. When comparing trusted tax services, check the assumptions behind the price rather than comparing the headline amount alone.
A fixed fee may depend on receiving reconciled records, a defined number of returns or information by a specified date. Ask whether applicable sales taxes and disbursements are included, when invoices are issued and whether a deposit is required. An estimate should be labelled as an estimate, with an explanation of what could change it.
The agreement should describe how work outside the original scope is approved. Reconstructing missing bookkeeping, amending an earlier return or responding to a CRA review may require a separate assignment. A useful approval process identifies the additional work and its expected cost before it proceeds, except where another arrangement has been explicitly agreed.
Do not assume ongoing advice is bundled into annual compliance. If you also need cash-flow forecasting, budgeting or help evaluating business decisions, discuss business advisory support separately. This gives both parties a clearer basis for deciding what advice is expected throughout the year.
Address confidentiality, document access and retention
An engagement letter should explain how confidential information will be handled and how documents should be exchanged. Trusted tax services should provide clear instructions for sending sensitive records rather than leaving clients to choose an informal sharing method.
Ask whether the firm uses outside service providers, how relevant disclosures are handled and who to contact with privacy questions. Where another person is involved in your business, the agreement should clarify who may receive information. A shareholder, spouse or bookkeeper should not be assumed to have unrestricted access simply because they know the client.
Record access also deserves attention. Distinguish client-provided documents and final deliverables from the firm’s internal working papers. Clarify how you will obtain copies, whether retrieval charges may apply and what happens to access when the relationship ends.
The CRA’s guidance on keeping records generally requires records to be kept for six years from the end of the last tax year to which they relate, with exceptions that can require longer retention. Using an accountant does not remove your responsibility to keep appropriate records. The letter should make the firm’s retention practices clear without suggesting they replace your own obligations.
Clarify what happens after filing or when the relationship ends
Post-filing support is a common source of misunderstanding. An assessment notice, a request for receipts and a formal audit involve different amounts of work. The letter should say whether the firm reviews notices automatically, responds only when asked or quotes separately for CRA enquiries.
Trusted tax services should also explain how a discovered error will be investigated and how any necessary correction will be handled. Avoid assuming that every amendment is included or that every reassessment means the preparer made a mistake. The cause and the agreed responsibilities matter.
Read any limitation-of-liability, indemnity or dispute-resolution provisions carefully. These clauses can affect your rights and deserve clarification before signing. If their meaning or consequences are unclear, obtain independent legal advice rather than relying on a quick verbal explanation.
Termination terms should cover how either party ends the engagement, payment for completed work and the status of unfinished assignments. Ask how outstanding deadlines will be communicated and how records or completed deliverables will be transferred. If a dispute arises near a filing deadline, do not assume the firm will continue working without confirmation. Get a clear written account of what remains to be done and who is responsible.
Frequently asked questions
Is an engagement letter the same as CRA authorization? No. The engagement letter defines the service relationship. CRA representative authorization allows specified access to tax information and services. Filing authorization, where required, is another separate step.
Does tax preparation include tax planning? Not automatically. When reviewing trusted tax services, look for an explicit description of any planning advice, its timing and its fee. Preparing a return based on completed transactions is different from advising you before a transaction takes place.
Should the letter guarantee that I will not be audited? No. An accountant cannot control whether the CRA selects a return for review or audit. The agreement should instead explain the work performed, the information relied upon and whether support for a later enquiry is included.
Can I ask for changes before signing? Yes. Ask the firm to clarify missing services, unclear responsibilities or fee assumptions. Material changes should be reflected in the signed letter or a written amendment, rather than left as informal assurances.
Do I need a new letter every year? That depends on the agreement. Some engagements cover one period, while others continue under renewal terms. Confirm the current scope whenever your business, ownership, reporting obligations or required services change.
Start with a clear agreement
Before engaging a firm, identify the returns you need, the condition of your records and the advice you expect beyond filing. Then compare those needs with the written scope, deadlines and fees.
Contact Reach Professional Accounting to discuss your business’s accounting, tax and advisory needs in Oakville or the GTA. Ask for an engagement letter that clearly reflects the services agreed before work begins.