Customer deposits improve cash flow, but they are not automatically sales or money available to spend. Effective business bookkeeping services distinguish funds held for future work from earned revenue, track each customer’s balance and apply the correct GST/HST treatment. Without that separation, an Ontario business can overstate profit, issue an incorrect final invoice or struggle to fund a refund.
The challenge is especially common for contractors, custom manufacturers, event businesses and other companies that collect money before delivery. A payment may secure a booking, fund materials or settle part of an invoice. Those arrangements can require different accounting and tax treatment, even when everyone casually calls the payment a deposit.
The solution is a documented process connecting the contract, receipt, customer account and final invoice. Here is what that process should include for an Oakville or GTA business.
What business bookkeeping services should track for each deposit
Start with the agreement, not the bank transaction description. The word “deposit” on an e-transfer does not establish whether the money is refundable, whether it is advance consideration for a supply or when revenue should be recognized.
Under accrual accounting, money received before the related goods or services are provided generally creates a liability rather than immediate revenue. The precise account and recognition timing depend on the arrangement and the applicable accounting framework. Some project revenue is recognized as work progresses, rather than entirely at completion.
For project-based trades, scope matters. For example, painting and decorating services can cover interior walls, exterior surfaces or epoxy flooring. A Canadian contractor offering several services should connect each receipt to the specific approved quote, not a general sales category.
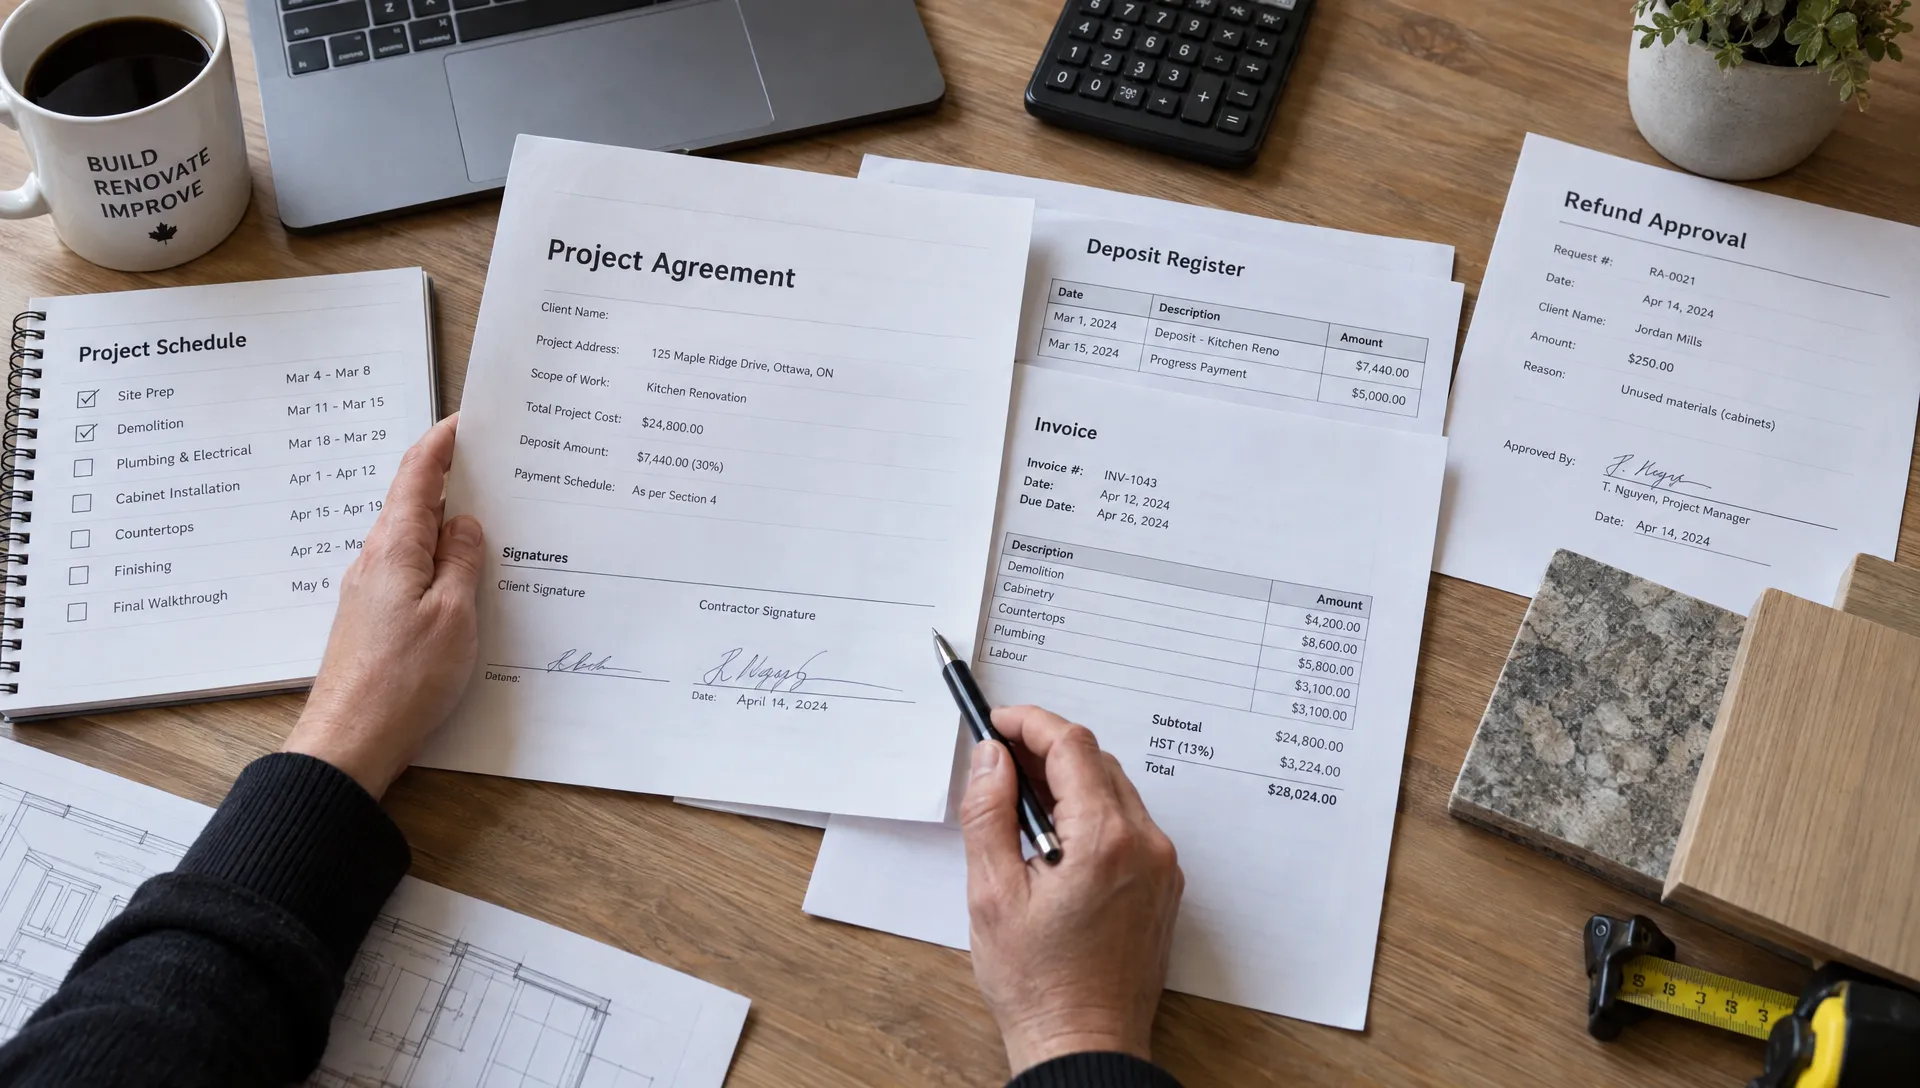
A useful deposit register records:
- Customer and project: Legal customer name, job reference and approved scope.
- Payment details: Receipt date, gross amount, payment method and transaction reference.
- Contract terms: Refund conditions, application terms and relevant milestones.
- Accounting status: Liability balance, tax treatment, applications, refunds and remaining amount.
Keep the contract and receipt accessible from the accounting record where practical. This gives the bookkeeper evidence for the entry and gives the business a clear answer when a customer asks how much remains on account.
Separate revenue recognition from GST/HST timing
Canadian sales-tax timing does not always follow revenue recognition. Your business bookkeeping services should assess those questions separately rather than use one rule for every advance receipt.
For GST/HST purposes, a genuine deposit generally does not trigger tax when received. Tax applies when the deposit is applied as consideration for the purchase. An advance payment that is actually consideration for a taxable supply follows the usual GST/HST timing rules, generally the earlier of payment and when the amount becomes due.
The CRA’s guide for GST/HST registrants explains the treatment of deposits. The contractual substance matters, so labelling a payment “refundable” or “non-refundable” does not, by itself, settle every accounting or tax question.
For an Ontario business, 13% HST may apply to a taxable supply made in Ontario. However, the customer’s address alone does not determine the rate. Place-of-supply rules, the nature of the supply and the supplier’s registration status must be considered. Work involving other provinces may also require separate provincial sales-tax analysis.
A deposit liability does not necessarily mean that GST/HST can wait. Likewise, collecting GST/HST does not automatically mean the underlying payment is earned revenue. Establish the treatment when the contract is set up, then apply it consistently to receipts and invoices.
Record the receipt, invoice and application separately
Accurate business bookkeeping services preserve each step of the transaction. Recording the incoming payment directly to sales, then recording the full invoice to sales again, can double-count revenue.
Consider a simplified example involving an Ontario GST/HST registrant. A customer pays a genuine $2,000 security deposit toward a $5,000 taxable project. Assume the deposit is not advance consideration, no earlier invoice triggers tax and the business earns the full project revenue on completion. At that point, the deposit is applied against the final invoice.
| Stage | Debit | Credit |
|---|---|---|
| Receive the deposit | Bank: $2,000 | Customer deposits liability: $2,000 |
| Complete the work and issue the invoice | Accounts receivable: $5,650 | Revenue: $5,000; HST payable: $650 |
| Apply the deposit | Customer deposits liability: $2,000 | Accounts receivable: $2,000 |
| Collect the remaining balance | Bank: $3,650 | Accounts receivable: $3,650 |
The final invoice totals $5,650, including HST. Applying the $2,000 deposit leaves $3,650 owing.
This example is not a template for every advance payment. Different terms, earlier billing or progress-based revenue recognition can change the entries and timing.
Accounting software may use a customer credit, deposit item or clearing workflow. Whatever the method, confirm that it produces the intended general-ledger balances and customer statement. An automated bank-feed match is not enough to establish that the accounting is correct.
Reconcile customer deposits every month
A bank reconciliation confirms cash movements. It does not prove that the business owes the correct amount to each customer. Reliable business bookkeeping services also reconcile the deposit register to the general ledger.
Use a monthly roll-forward:
Opening deposit liability + new deposits − amounts applied − refunds − other supported releases = closing deposit liability.
Record any related GST/HST separately where required. Every movement should have a customer reference and supporting document, including a refund approval, final invoice or documented cancellation.
For example, an opening liability of $18,000 plus $7,000 received, less $5,500 applied and $1,000 refunded, produces an $18,500 closing liability. The individual customer balances should total that same amount.
Investigate old balances rather than carrying them forward indefinitely. They may represent delayed projects, missed applications, unresolved refunds or transactions posted to the wrong customer. A negative balance can indicate an over-application or another posting error.
Payment processors add another reconciliation layer. A $1,000 customer payment may reach the bank as a smaller settlement after fees. Record the gross customer receipt and the processing fee separately so the customer receives full credit.
This is also why monitoring automated bank feeds matters. Missing transactions, duplicates and incorrect matches can leave the bank balance looking plausible while individual deposit records remain wrong.
Handle refunds, scope changes and forfeitures carefully
Exceptions are where business bookkeeping services need clear approval rules. A cancellation, additional work request or customer substitution should not be resolved by editing the original receipt without an explanation.
For a full refund of an unused genuine deposit, the basic accounting generally reduces the deposit liability and cash. If GST/HST was previously accounted for, the refund may also require a tax adjustment and appropriate documentation. Refunds should follow an approved process, with independent verification of any changed banking details.
When the scope changes, retain the original agreement and the approved variation. Update the project allocation and payment schedule without losing the history. Moving money between jobs should require evidence that the customer authorized the transfer, particularly where different legal customers are involved.
A forfeited deposit needs separate review. Contract enforceability, revenue recognition and GST/HST treatment are distinct issues. A forfeiture can create a GST/HST obligation even if the planned work never occurs, so moving the entire balance straight to revenue may be incorrect.
Similarly, a project that has been inactive for months does not automatically make its deposit available as income. Establish whether the business still owes work, goods or a refund. Escalate disputed amounts for accounting and, where appropriate, legal advice before releasing the liability.
Use deposit reports to assess available cash
A healthy bank balance can hide future commitments. Decision-focused business bookkeeping services show both the cash received and the work or refund obligations attached to it.
Suppose a business has $40,000 in its operating account, including $25,000 of customer deposits for work not yet started. That does not mean it has $40,000 available for owner withdrawals, debt repayment or unrelated purchases. Materials, labour, subcontractors and potential refunds still need funding.
A useful management report connects unapplied deposits with expected project costs and delivery dates. It should also identify deposits associated with delayed projects, cancellation requests and uncertain completion schedules. This helps the owner assess whether incoming money is supporting the work it relates to or covering shortfalls elsewhere.
Separate bank accounts may help internal cash discipline, but they do not replace customer-level records. Nor should a business assume that every deposit must be held in trust, or that none must be. Trust, segregation and permitted-use requirements depend on the industry, contract and applicable law.
The practical objective is visibility: know what has been earned, what remains owed and what cash must support the remaining commitments.
Define the bookkeeping provider’s responsibilities
Before hiring business bookkeeping services, ask how the provider will manage deposits from receipt through completion, not simply whether it offers transaction categorization.
The engagement should identify who reviews contract terms, maintains the deposit register, reconciles balances and approves exceptions. It should also explain when the bookkeeper refers a question to the accountant, tax adviser or legal counsel. Bookkeeping records support those decisions, but do not replace specialized advice.
Request a clear distinction between recurring work and additional fees. Monthly deposit reconciliation may be included in one proposal but treated separately in another. Historical cleanup, contract-by-contract tax review, software configuration and high volumes of refunds can affect the workload and price. Compare quotes against your actual transaction complexity rather than an hourly rate alone.
Access controls deserve equal attention. Ask about professional qualifications relevant to the work, insurance, confidentiality and subcontractor access. Where practical, separate the person who records a refund from the person who authorizes or releases it. These bookkeeping controls for protecting financial data also help preserve a reliable transaction history.
If you are switching providers, transfer the detailed customer deposit schedule, supporting agreements and transaction history, not just a trial balance. Agree on a cutover date and reconcile opening balances before the new provider starts routine processing.
Frequently asked questions
Are customer deposits counted as revenue? Not automatically. Under accrual accounting, amounts received before the related goods or services are provided generally remain liabilities until revenue recognition is appropriate. The contract and applicable accounting policy determine the treatment, not the bank receipt alone.
Do I charge HST when I receive a deposit? A genuine deposit generally does not trigger GST/HST until it is applied as consideration. An advance payment for a taxable supply may trigger tax earlier under the usual timing rules. Have the arrangement reviewed before relying on the word “deposit.”
Can bookkeeping software track deposits automatically? Software can help record receipts and apply customer credits, but configuration and review remain necessary. Your business bookkeeping services should verify the liability account, tax codes, customer allocation and final invoice treatment rather than rely solely on bank-feed suggestions.
What should appear on the final invoice? Show the agreed charges, applicable tax, deposit applied and remaining balance clearly. The accounting must avoid recognizing the same receipt as revenue twice. The invoice presentation and entries should reflect whether tax was already accounted for on an earlier payment.
What if a customer never returns? Do not automatically write the deposit into income. Review the agreement, refund obligations, applicable law and potential GST/HST consequences. Keep evidence supporting any decision to release the balance.
Put a clear deposit process in place
Reach Professional provides bookkeeping, accounting and tax planning support for businesses in Oakville and the GTA. If customer advances are difficult to reconcile, discuss your current workflow through Reach Professional’s bookkeeping services. Start with the deposit register, contract terms and unresolved balances so the scope of work addresses the actual gaps.