A CPA newsletter can do more than keep the business owner informed. Used well, it gives your team a shared starting point for understanding cash flow, asking better questions and spotting problems before they reach the accountant’s desk. The key is to turn one relevant article into a short discussion and one clearly assigned action, rather than forwarding the entire issue with a request to “please read.”
For an owner-led business, this can fit into an existing monthly meeting. You do not need a training platform or a finance background for every participant.
Start with a learning goal, not a reading assignment
Before sharing an article, decide what someone should be able to do differently after reading it. “Understand accounting better” is too broad to guide a useful conversation.
A practical goal might be helping project managers distinguish an invoice from a payment, helping supervisors recognize a payroll question that needs escalation or helping sales staff understand why an agreed payment term matters.
The goal is better judgement within each person’s role, not turning every employee into an accountant. Staff should know what to notice, what information to gather and when to ask for help. Accounting interpretations, tax positions and changes to financial controls still belong with the people authorized to make those decisions.
Choose the audience accordingly. A cash collection discussion may need operations and accounts receivable staff, while a payroll update may be relevant only to managers and payroll administrators.
Choose one CPA newsletter item worth discussing
Select the item that connects most directly to a decision or recurring problem in your business. A short explanation of working capital may be more useful this month than a detailed tax development that does not affect your company.
Use three filters when choosing:
- Relevance: Does the topic connect to work this group actually performs?
- Application: Can the team test its understanding against a realistic situation?
- Authority: Is it clear which details need confirmation before anyone changes a process?
For Canadian tax updates, check the publication date, jurisdiction and effective date. Also distinguish a proposal from an enacted measure. An older article can still explain a concept, but it should not be the sole basis for a current compliance decision.
Reach Professional’s tax and accounting insights for Canadian business owners can provide discussion topics. Select one item, share its source link and tell participants which question you want them to consider before the meeting.
Run a focused 20-minute discussion
Treat the CPA newsletter as a prompt for active learning, not a script to read aloud. Send the selected article in advance with one question: “Where could this issue show up in our work?”
The following agenda is a suggested starting point. Adjust it to the complexity of the topic and the people involved.
| Time | Activity | Expected output |
|---|---|---|
| 3 minutes | Explain the concept in plain language | A shared definition |
| 5 minutes | Apply it to a fictional or anonymized business situation | A connection to everyday work |
| 7 minutes | Discuss the appropriate response and its limits | A proposed action or question for the accountant |
| 5 minutes | Confirm an owner and a review date | A documented next step |
Ask a participant outside the finance function to explain the takeaway in their own words. This reveals misunderstandings that a general “Does everyone understand?” often leaves hidden.
For example, someone might correctly explain that a profitable month does not necessarily mean there is enough cash available for every planned purchase. The next step is identifying which information they should check, not asking them to make financing decisions.
End with one action. If the discussion produces several technical questions, record them for follow-up rather than trying to resolve them through group opinion.
Give each role a useful responsibility
A CPA newsletter becomes a team learning tool when the lesson has a clear place in someone’s work. Without ownership, a useful discussion can end with everyone assuming somebody else will act.
Assign a facilitator to keep the session focused, a subject owner to confirm the accounting implications and an action owner to carry out the approved next step. In a small business, one person may fill more than one role. What matters is that the responsibilities are explicit.
Cross-functional discussions also need clear handoffs. A customer service employee may identify an invoice dispute, but that does not automatically give them authority to issue a credit or change payment terms.
For businesses involving customer-facing teams, this guide to structuring a CX team for scale offers a useful parallel: map the work, clarify responsibilities and establish a regular operating rhythm. Apply that principle to financial learning by defining who notices an issue, who assesses it and who approves a response.
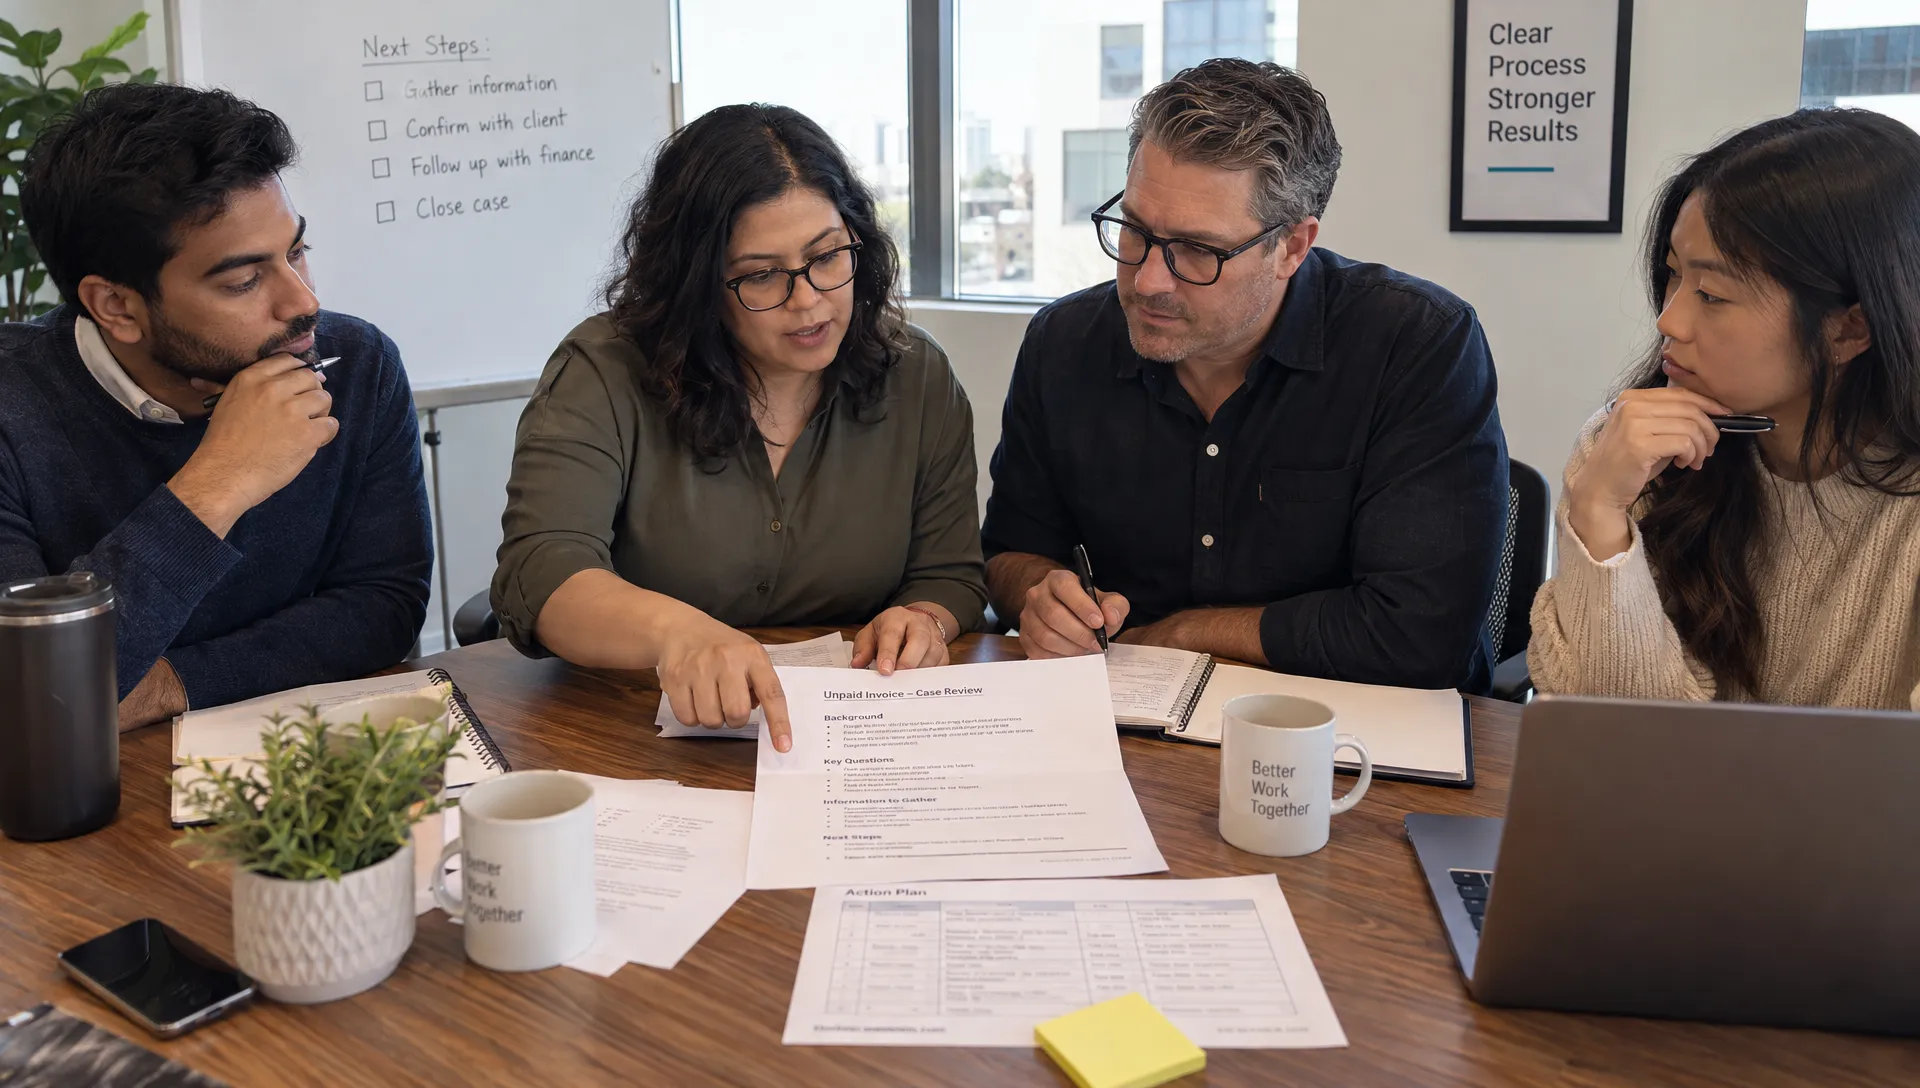
Work through an example: an unpaid invoice
Suppose your CPA newsletter explains the difference between revenue and cash collected. Rather than repeating the definitions, give the team a fictional situation: a completed job has been invoiced, the customer disputes one charge and payment has not arrived.
Ask participants what they would need to establish before taking action. Operations may need to confirm the work performed. The customer-facing employee may need to document the dispute. Accounts receivable may need to check the invoice, payment history and existing collection notes.
The learning point is that “the job is finished” does not answer every financial question. Nor should a payment delay automatically lead to a credit, a write-off or a change in the accounting records.
A suitable action could be to test a standard dispute handoff on the next applicable case. The handoff would capture the invoice reference, the customer’s concern, the supporting information and the person responsible for reviewing it. An authorized manager would approve any change to the process.
At the next meeting, check whether the handoff reduced missing information or duplicated follow-up. This tests whether the lesson changed a working habit without claiming that a short discussion can solve every collection problem.
Keep a short learning record
Capture the CPA newsletter discussion in a shared note that takes only a few minutes to complete. The record should make the decision easy to find later, especially for staff who could not attend.
Use a simple template such as this:
| Field | What to record |
|---|---|
| Source and date | Article title, link and publication date |
| Learning goal | What participants should recognize or do differently |
| Business application | The situation discussed, without unnecessary personal details |
| Decision status | Approved action, proposed change or question awaiting advice |
| Owner and review date | Who will follow up and when |
| Follow-up result | What happened and whether further action is needed |
Keep learning notes separate from approved policies. A discussion summary should not accidentally become an instruction to change payroll, tax treatment or accounting procedures.
Use fictional or properly anonymized examples wherever possible. Avoid putting employee pay, banking details or identifiable customer information into broadly accessible training notes. Link to the original article rather than copying an entire publication into a shared folder without permission.
Pilot the approach for 30 days
Start with one team and one topic. A CPA newsletter does not need to become a company-wide training programme immediately.
In the first week, select the article, define the learning goal and choose a relevant example. Ask the subject owner to flag any technical boundaries before the discussion takes place.
In the second week, hold the session and record one approved action. Make the action small enough to test during normal work, such as using a revised handoff note or bringing a specific question to the next finance meeting.
During the remaining weeks, check whether the action happened and whether staff encountered confusion. At the end of the month, decide whether to keep, adjust or stop the practice.
If the issue requires professional advice, the successful outcome may simply be a well-prepared question with the necessary records attached. That is more useful than a team confidently implementing an unverified interpretation.
Measure understanding and application
You do not need a complicated training scorecard. Start with one learning check and one process check.
For the learning check, ask a participant to explain the concept or describe when they would escalate a similar issue. For the process check, review whether the agreed action was completed and whether the next handoff contained the required information.
Attendance and email opens can show participation, but they do not establish understanding. Likewise, a faster payment after one discussion does not prove the session caused it. Look for observable changes in behaviour and use the findings to choose the next topic.
Frequently asked questions
How often should we discuss a CPA newsletter? A monthly discussion is a practical starting point when the publication arrives monthly. Skip topics that do not apply to the team rather than holding a meeting simply to maintain the schedule. Urgent compliance matters need timely review outside that routine.
Should everyone read the entire issue? Usually not. Share one relevant article with a clear question. People who need broader context can read more, while the group discussion stays focused on a decision or behaviour connected to their work.
Can these discussions count toward a CPA’s CPD requirements? Do not assume that attendance or reading automatically qualifies. A CPA should check the applicable provincial body’s current continuing professional development requirements, including relevance, documentation and verifiability. Keep workplace learning records, but assess CPD eligibility separately.
What if the team disagrees about the advice? Record the uncertainty and refer it to the appropriate accountant or authorized decision-maker. Avoid changing financial procedures until the relevant facts and interpretation have been confirmed.
Put the next issue to work
Use the next issue of Reach Professional’s monthly business newsletter to choose one relevant lesson, discuss one realistic situation and assign one follow-up. Keep the first attempt small enough to repeat.
When a discussion reveals a broader planning or decision-making question, Reach Professional’s business advisory services can help you work through the financial implications before changing how the business operates.