You need financial accounting advisory services when your financial records no longer give you enough confidence to make an important business decision. That might happen before a financing application, during rapid growth or when reported profit does not seem to translate into cash in the bank.
For business owners in Oakville and across the GTA, the trigger is often practical rather than technical: you are considering hiring, expanding or borrowing, but cannot clearly explain what the business can afford. Advisory support helps connect the numbers to those decisions. The key is knowing when routine accounting is enough and when you need a deeper assessment.
What financial accounting advisory services actually do
Financial accounting advice helps a business improve the reliability of its reporting, understand accounting issues and use financial information to evaluate decisions. Depending on the engagement, it can include reviewing accounting policies, resolving reporting problems, analysing cash flow or preparing financial information for lenders and investors.
It is different from simply recording transactions or preparing a year-end tax return. Bookkeeping captures activity. Financial reporting organizes that activity into statements. Advisory work examines whether the information is appropriate for its purpose and what it means for the next decision.
There is also overlap with CFO advisory, but the two are not identical. CFO support typically extends further into budgeting, financing strategy and ongoing financial management. A technical accounting issue may need specialist advice without requiring an ongoing CFO relationship.
If your immediate need is dependable financial statements, Reach Professional’s accounting services are a relevant starting point. Financial accounting advisory services become useful when you also need to resolve uncertainty about those statements or their implications.
Advisory work does not automatically provide assurance. A compilation, review engagement and audit serve different purposes. If a lender requires a particular report, confirm that requirement before commissioning the work.
Six signs your business needs advice beyond routine accounting
1. You are profitable on paper but consistently short of cash
Profit and cash flow measure different things. Sales may be recorded before customers pay, inventory can absorb cash before it sells and loan principal repayments reduce cash without appearing as an operating expense.
An occasional timing gap does not necessarily call for a major engagement. A recurring gap that you cannot explain does.
Financial accounting advisory services can help identify whether the problem comes from collection delays, working capital requirements, debt payments or an accounting error. That distinction matters because each cause needs a different response.
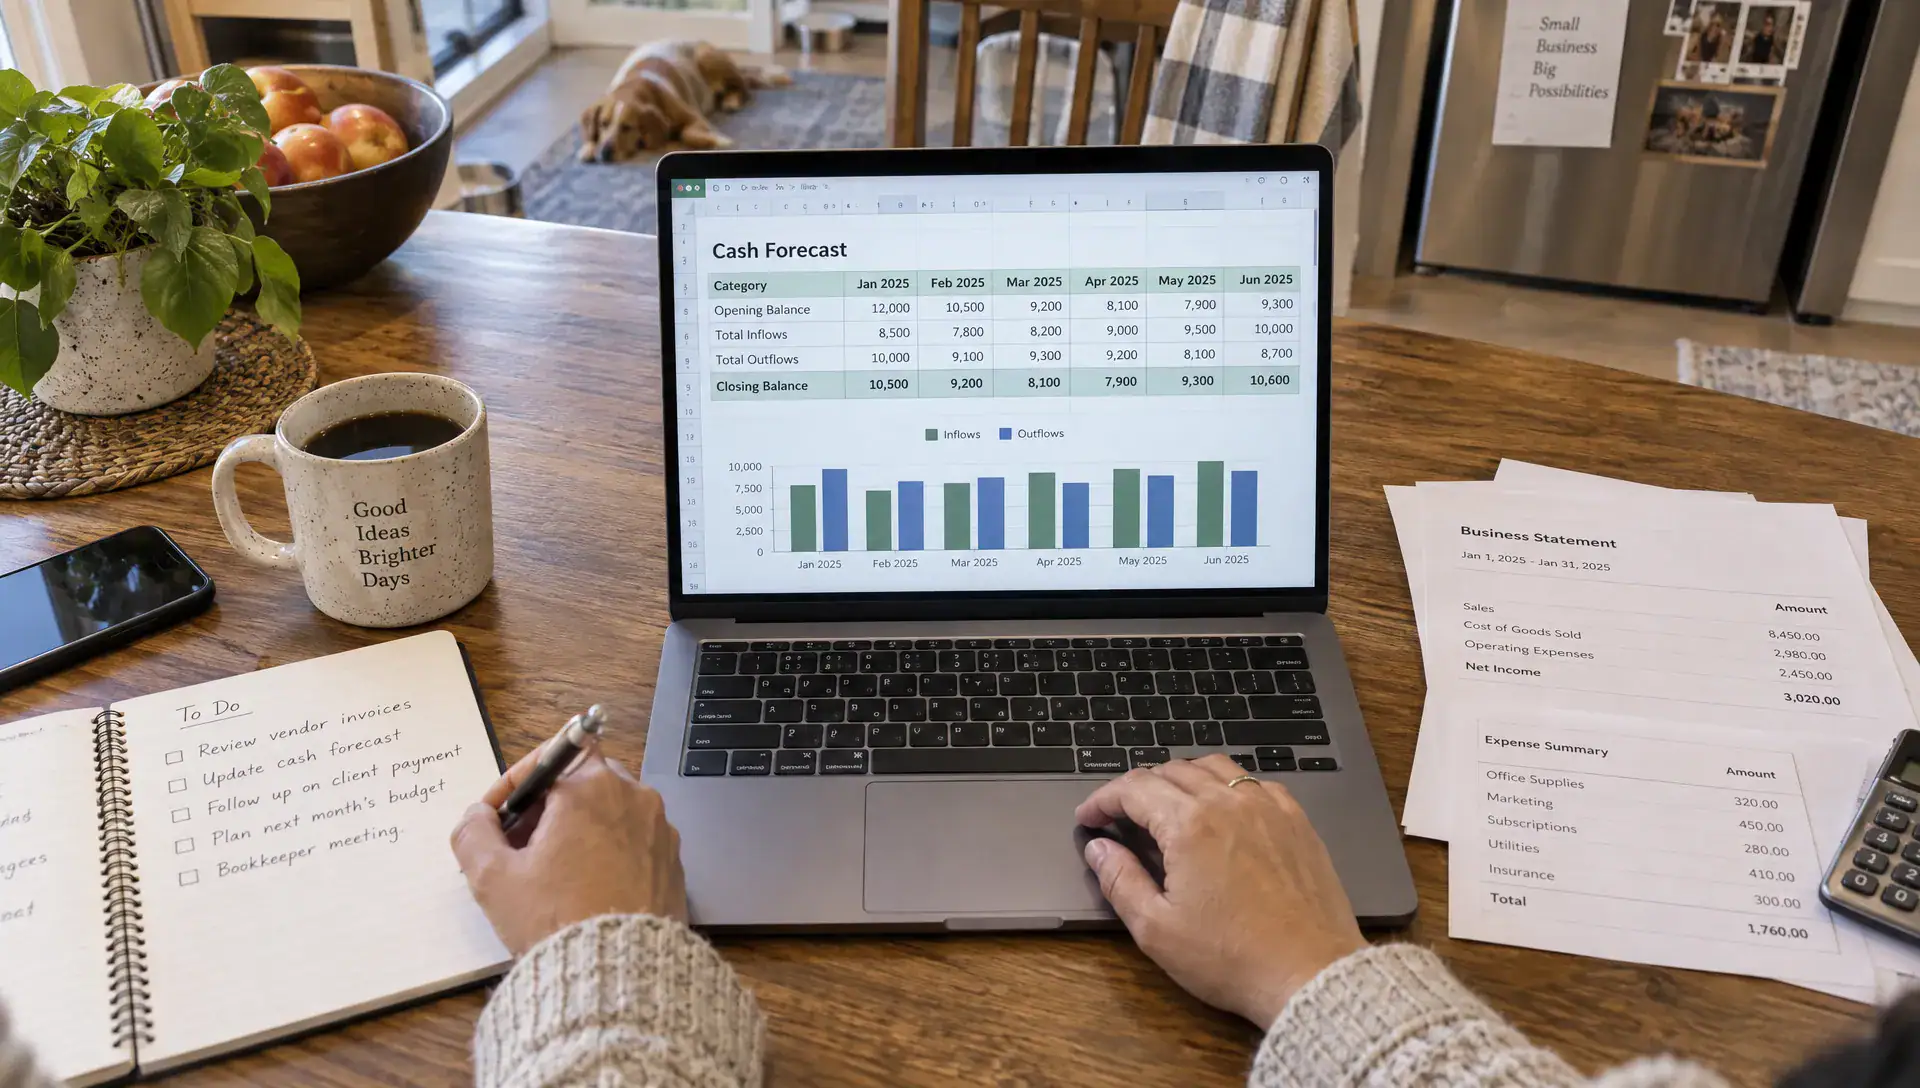
For example, a growing service business might report strong earnings while waiting months for customers to pay. A useful engagement could reconcile the reported profit to cash movements and build a short-term cash forecast. Hiring more staff before understanding that gap could intensify the pressure.
2. You cannot rely on your monthly numbers
Warning signs include unexplained account balances, frequent adjustments after reports are issued or large differences between your bookkeeping records and year-end financial statements.
Ask whether your reports consistently include bank reconciliations, outstanding receivables, unpaid supplier invoices and relevant accruals. Depending on the business, inventory, work in progress and deferred revenue may also require attention.
If these items are missing or inconsistent, the first priority may be fixing the underlying accounting process rather than creating more forecasts.
A useful adviser should distinguish a one-time cleanup from a recurring reporting weakness. For example, unclear responsibility for month-end adjustments can create the same problem every month. Correcting the balance once will not resolve that process failure.
3. A lender or investor needs information you cannot confidently provide
Financing discussions often expose gaps that were manageable internally. A bank may ask for historical financial statements, forecasts, details of existing debt or explanations of significant changes in performance.
Before applying, establish exactly what the recipient needs, including the reporting period, accounting basis and level of assurance. Do not assume that internally prepared statements will satisfy every lender.
Financial accounting advisory services can help you assess reporting gaps and explain how the proposed financing affects cash flow and repayment capacity. Where borrowing includes financial covenants, you also need to understand their definitions and calculation requirements.
A business considering equipment financing, for instance, should examine more than the monthly payment. It needs to assess installation costs, operating expenses and the effect of slower-than-expected revenue. Advice is most useful before commitments are signed, while there is still room to adjust the plan.
4. Growth is making margins harder to understand
Revenue growth can hide weakening profitability. More locations, employees, product lines or customer contracts create additional costs that may not be visible in a simple income statement.
You may need advice if you cannot tell which services generate a reasonable return, whether pricing covers delivery costs or how much overhead a new location would add.
The objective is not to allocate every dollar with artificial precision. It is to identify the costs that genuinely change the decision.
For example, an owner evaluating a second location needs to separate existing overhead from new rent, staffing and equipment costs. A forecast based only on the first location’s average margin may miss those differences.
5. Your transactions have become more complex
A new lease, acquisition, foreign-currency contract or change in ownership can introduce accounting questions that ordinary bookkeeping routines do not address. Revenue arrangements involving deposits, milestones or bundled services can also require closer assessment.
Canadian reporting requirements are not interchangeable. The Accounting Standards Board develops Canadian accounting standards for private enterprises and not-for-profit organizations. The appropriate framework and accounting treatment depend on the entity and its reporting requirements.
Financial accounting advisory services are worth considering before an unfamiliar transaction is finalized, particularly if its accounting treatment could affect reported earnings, debt covenants or information provided to investors.
This does not mean every unusual invoice needs specialist attention. Focus on transactions that are material, recurring or important to an external reader of your financial statements. Bring the underlying agreements, not just the bookkeeping entries.
6. A sale, succession plan or board decision is approaching
Major decisions require numbers that can withstand questions from someone outside the day-to-day business. A prospective buyer may challenge unusual expenses, related-party transactions or inconsistent revenue recognition. A successor may need a clearer picture of debt, cash requirements and sustainable earnings.
For charities and not-for-profit organizations, the trigger may be a significant funding agreement, restricted contributions or a board decision involving long-term commitments. Advice should reflect the organization’s reporting obligations and funding terms rather than applying a commercial business model without adjustment.
Start before the decision becomes urgent. Resolving unclear balances or gathering missing agreements takes time, and rushed corrections can distract from negotiations. Early preparation also helps distinguish a genuine financial issue from a documentation problem.
How urgent is your need for advice?
The strongest signals combine unreliable information with a decision that has meaningful financial consequences. Use this triage framework as a starting point, not as a substitute for reviewing your circumstances.
| Situation | Sensible next step | Timing |
|---|---|---|
| Reports are reliable and no major change is planned | Maintain regular accounting and revisit advice when circumstances change | Routine review |
| Monthly reports contain recurring unexplained differences | Assess reconciliations, accounting policies and the close process | Before relying on the reports |
| Expansion or financing is under consideration | Review forecasts, reporting requirements and downside scenarios | Before making commitments |
| An unfamiliar material transaction is proposed | Obtain advice on its accounting and reporting implications | Before signing, where possible |
| Payroll, tax remittances or debt payments may be missed | Seek prompt professional help to assess cash needs and obligations | Immediately |
You do not need to wait until every indicator is present. Financial accounting advisory services are most valuable when they address a specific uncertainty early enough to change the outcome.
Choose the right scope, not the largest engagement
A clearly defined project is often more appropriate than an open-ended advisory arrangement. If the problem is one accounting treatment or a financing package, start with a scoped assessment and agreed deliverables.
Ongoing support makes more sense when decisions recur, reporting needs are changing or management needs regular help interpreting results. A growing business might need monthly financial review and forecasting, while a stable business may only need advice around major transactions.
Reach Professional’s business advisory and fractional CFO services are relevant when your needs extend into financial planning and ongoing decision support. The right starting point still depends on the issue you are trying to solve.
Before agreeing to financial accounting advisory services, ask what the engagement will produce: corrected reporting, an accounting assessment, a forecast or a recommendation supported by analysis. A deliverable should answer a business question, not merely add another report to your inbox.
What to prepare for the first conversation
Bring enough information to explain both the financial position and the decision ahead. Recent financial statements, a current trial balance, bank reconciliations, receivables and payables ageing reports are useful starting documents. For a transaction-specific question, include the relevant contracts or lender correspondence.
You do not need perfect records before asking for help. Be clear about what is missing, how current the information is and which figures you do not trust.
The most useful preparation is a short decision brief covering:
- The decision: What are you considering, and what alternatives are available?
- The deadline: When must you act, and which commitments have already been made?
- The uncertainty: Which numbers, assumptions or accounting treatments need clarification?
- The outcome: What would allow you to proceed, revise the plan or stop?
For financial accounting advisory services, this context helps define the scope and prevents technical work from becoming disconnected from your actual need.
Also ask who will complete the work, what information they require and whether other specialists should be involved. Legal advice, tax advice and assurance work may require separate scopes, even when they relate to the same transaction.
Frequently asked questions
Do small businesses need financial accounting advice? Sometimes. Complexity and decision risk matter more than business size alone. A small company entering a significant lease or seeking financing may need targeted advice, while a larger business with reliable reporting and stable operations may need less frequent support.
Can my existing accountant provide this advice? Possibly. Ask whether they have experience with your specific issue and whether the work falls within your current engagement. Preparing annual statements or tax returns does not automatically include transaction analysis or ongoing forecasting.
Will advisory services fix poor bookkeeping? They can help diagnose the problem and recommend corrections, but the scope must specify who will perform the cleanup and maintain the records afterwards. Reliable advisory work depends on sufficiently accurate underlying information.
How much does an engagement cost? Fees depend on complexity, record quality, urgency and the agreed deliverables. Request a written scope that explains pricing, assumptions and how additional work will be approved. Compare the proposed work, not just the headline fee.
Start with the decision you need to make
If you cannot confidently explain your cash position, meet a reporting request or evaluate a significant commitment, it may be time for financial accounting advisory services. Start by identifying the uncertainty and the deadline, then seek the level of support that addresses both.
Reach Professional serves Oakville and GTA businesses with accounting, tax and advisory support. Book a conversation with Reach Professional to discuss your situation and determine an appropriate next step.